Debt Snowball vs Debt Avalanche: Which Pays Off Debt Faster?
Both methods use the same plan: pay the minimum on every debt, put every extra dollar on one target debt, and when it's gone, roll its payment into the next one. The only difference is the order.
- Snowball: smallest balance first. You get quick wins.
- Avalanche: highest interest rate first. You pay less interest.
A worked example
Three debts, with $395 a month to put toward them in total:
| Debt | Balance | APR | Minimum |
|---|---|---|---|
| Credit card | $2,000 | 22% | $60 |
| Car loan | $6,000 | 7% | $150 |
| Store card | $900 | 18% | $35 |
We simulated both methods month by month:
| Snowball | Avalanche | |
|---|---|---|
| First debt paid off | Month 6 (store card) | Month 11 (credit card) |
| Debt-free | Month 25 | Month 25 |
| Total interest | ≈ $963 | ≈ $936 |
Here the avalanche saves about $27, and the snowball gets you your first payoff five months earlier. The gap grows when a large balance also has the highest rate, and shrinks when rates are similar.
Which should you choose?
If you're likely to stick with it either way, the avalanche is mathematically cheaper. If motivation is the real risk, the snowball's early wins can be worth a little extra interest. The best method is the one you'll still be following in month 20.
Our planner lets you switch between the two methods with one dropdown and shows the payoff order, months and interest for each debt, so you can compare them with your own numbers.
General information, not financial advice.
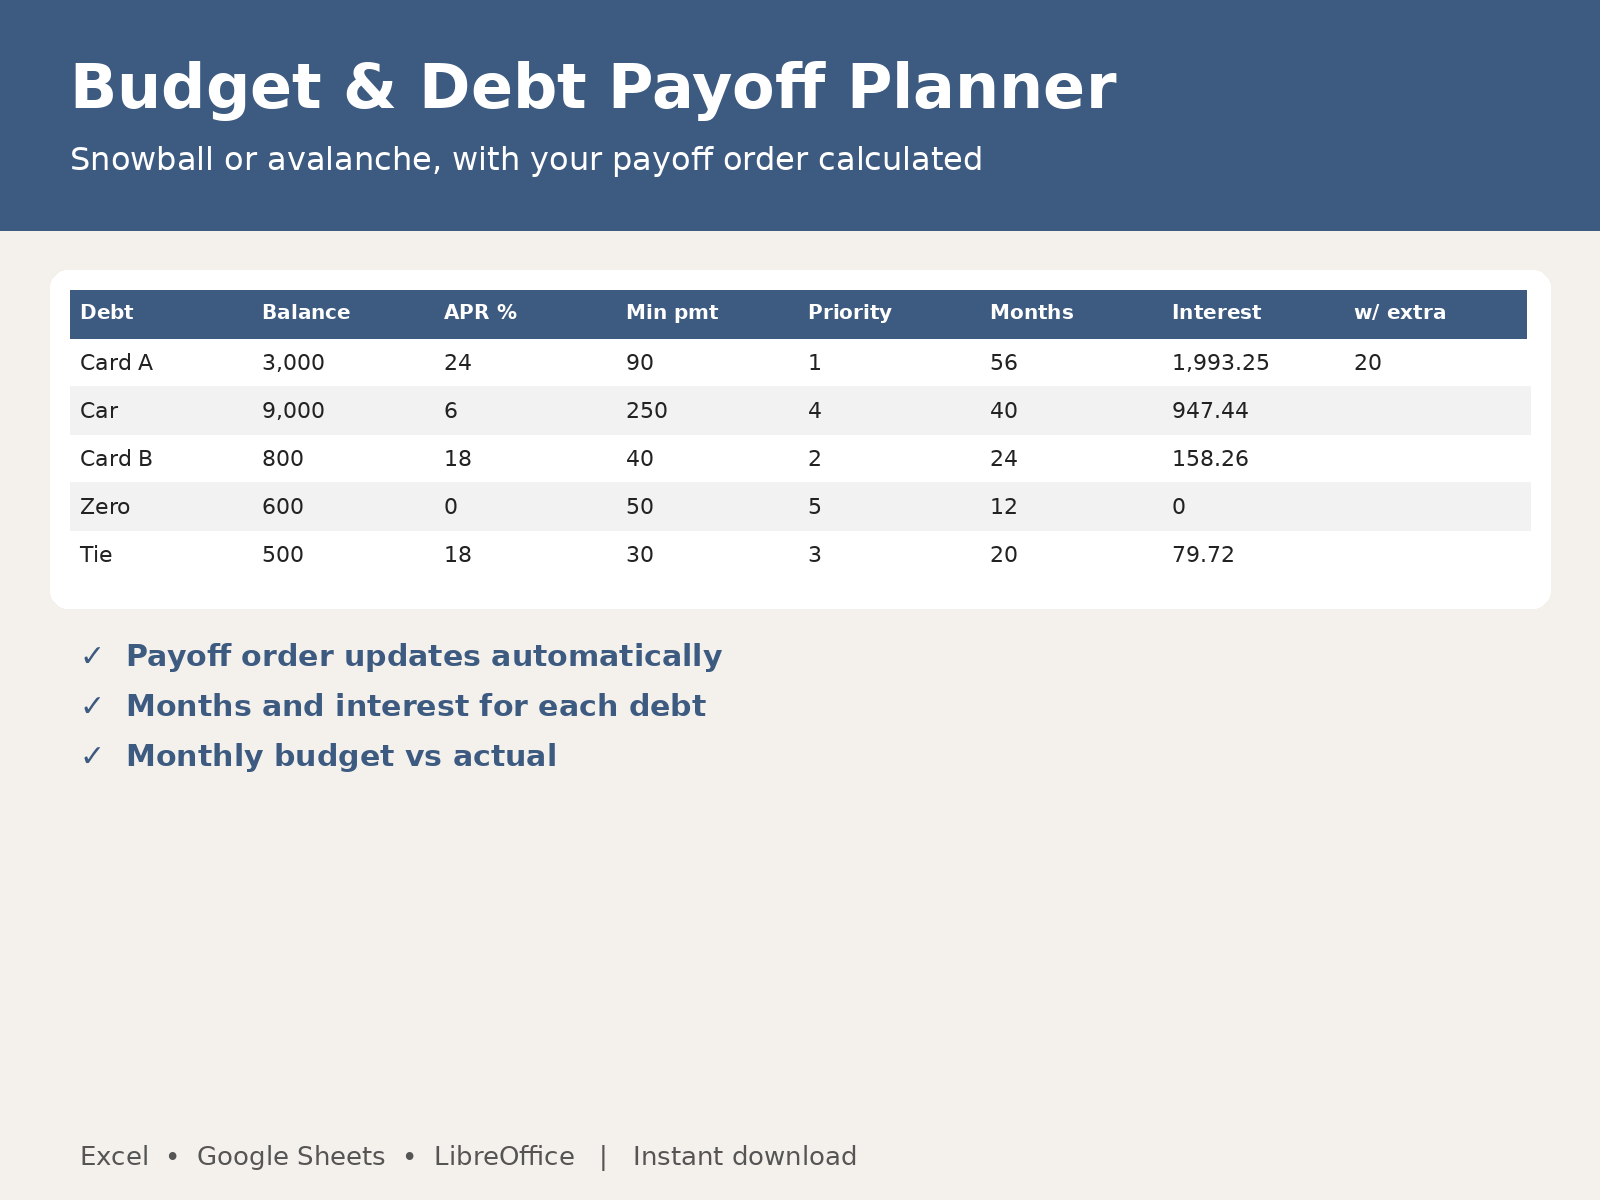
Budget & Debt Payoff Planner: do this math automatically in Excel or Google Sheets.
See the Budget & Debt Payoff Planner